Mississippi Gulf Coast towns at a glance
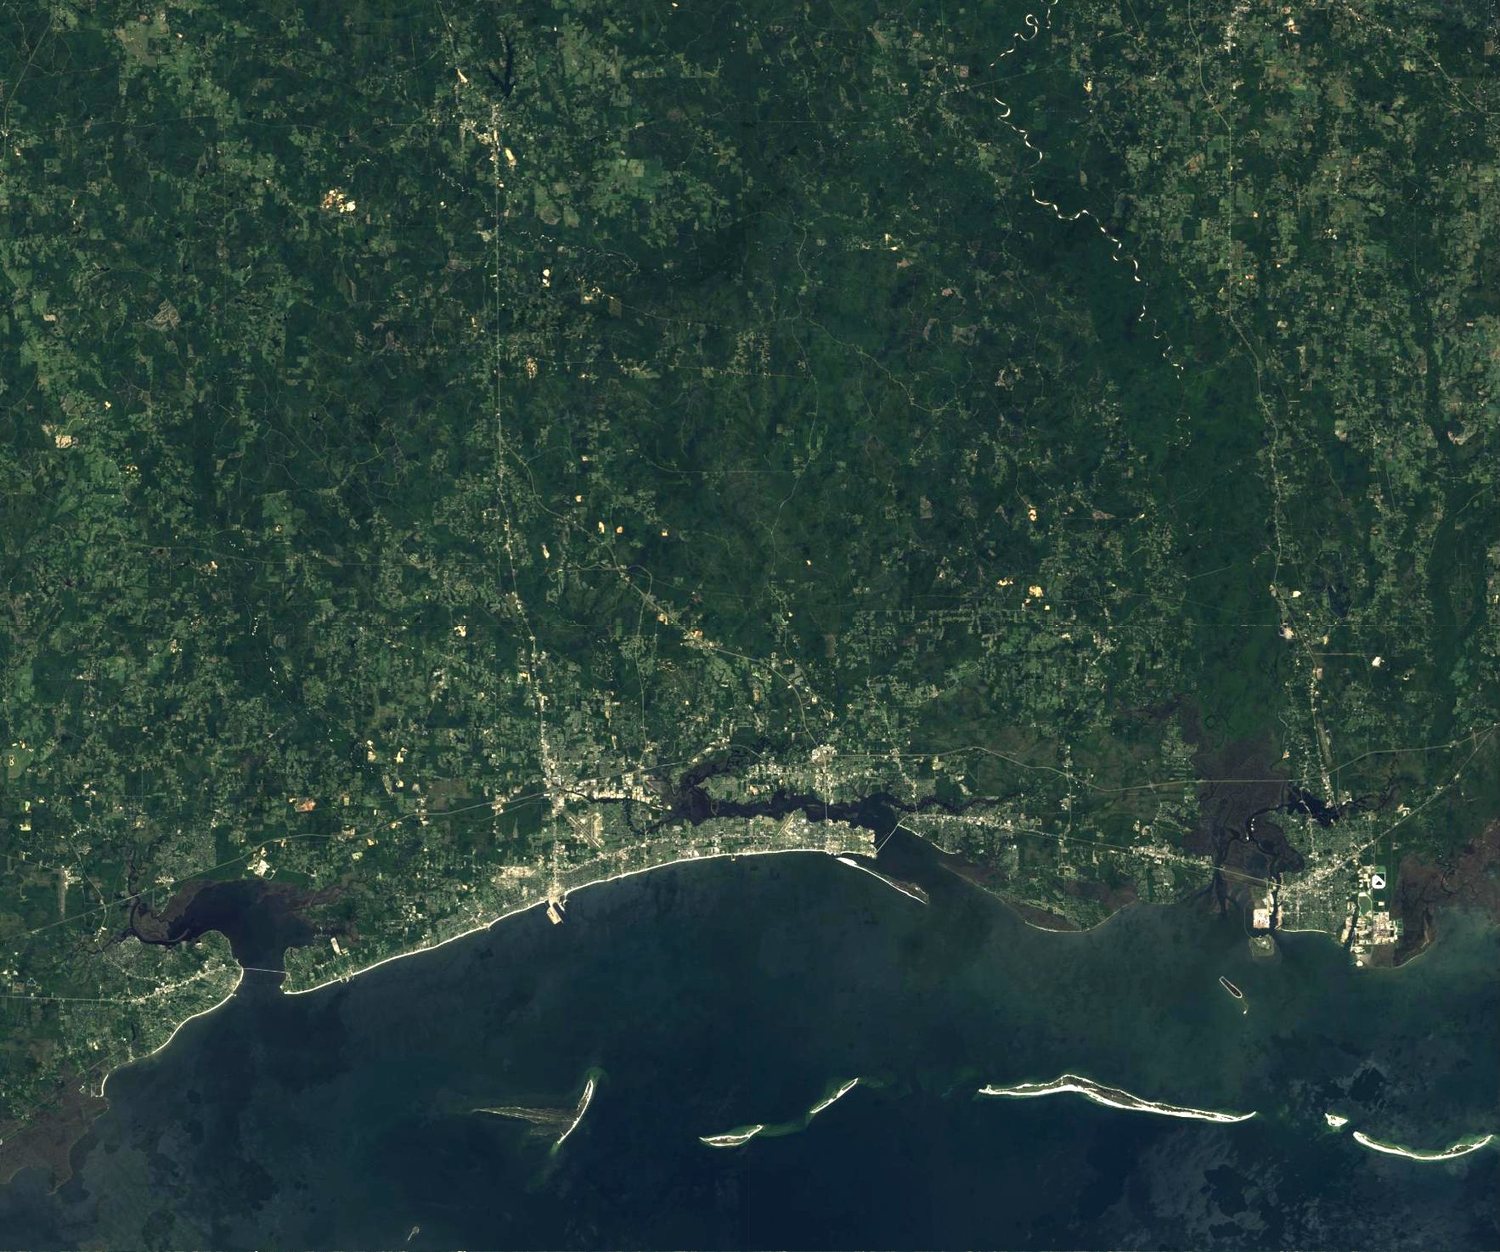
Twenty-six miles of the longest man-made beach on planet Earth, plus the barrier islands of Gulf Islands National Seashore. Here is what each town is like to live in.
Gulfport — The coast's commercial heart
Gulfport is where the Mississippi Gulf Coast gets things done — a real hospital system, every big-box store you actually need, casino lights at Island View, and a working harbor all inside the city limits. But Jones Park keeps its family-beach soul intact, with a fishing pier and splash pad steps from downtown. Big enough to have everything, small enough to still feel like home.
Nearby: Sam's Club, Memorial Hospital Gulfport, Gulfport Premium Outlets, Jones Park, Gulfport Harbor, Island View Casino
Biloxi — Casino lights, three centuries of history
Biloxi is the coast's glamour strip after dark — Beau Rivage, Hard Rock, IP, and Golden Nugget stack up along the Sound — but drive a few minutes west on Highway 90 and you're at Beauvoir, Jefferson Davis's white-columned beachfront estate, or standing under the Biloxi Lighthouse, lit since 1848 and still standing in the middle of the highway. Few places on Earth mix a casino skyline with this much real history.
Nearby: Merit Health Biloxi, Beau Rivage, Hard Rock Biloxi, IP Casino Resort, Golden Nugget Biloxi, Beauvoir Historic Estate, Biloxi Lighthouse, Ohr-O'Keefe Museum of Art, Town Green
D'Iberville — The coast's retail engine
If you need it, D'Iberville has it. The Promenade and Bass Pro Shops pull shoppers from three counties, and Le Moyne Landing's waterfront boardwalk on the Back Bay adds a marina-town evening scene nobody expects to find behind a shopping district. Convenience with a view — that's D'Iberville.
Nearby: The Promenade (Target, Best Buy, dining), Bass Pro Shops, Scarlet Pearl Casino Resort, Le Moyne Landing marina district
Ocean Springs — Gallery-town soul, quiet shoreline
Ocean Springs is the coast's artsy darling. Government Street's oak-shaded storefronts and the Walter Anderson Museum of Art give it a gallery-town feel you won't find anywhere else on this coast, and Front Beach stays calm and uncrowded — it's where the locals actually swim, not the tour buses.
Nearby: Walmart Supercenter & Neighborhood Market, Ocean Springs Hospital (Singing River), Walter Anderson Museum of Art, Fort Maurepas Park, Front Beach, Government Street district
Long Beach — College-town energy, harbor calm
This is home turf — the town Prescott Properties works out of, and it's easy to see why. The 500-year-old Friendship Oak on the USM Gulf Coast campus alone tells you how long people have loved this shoreline, and the harbor at sunset is where the locals actually gather, not the tourists. Long Beach sits dead center on the longest man-made beach on planet Earth — 26 engineered miles of white sand running right past your front door.
Nearby: Winn-Dixie, Walmart, Long Beach Harbor, USM Gulf Park campus, Friendship Oak, Historic downtown district, Long Beach High School
Pascagoula — A true working river city
Pascagoula earns its keep — Ingalls Shipbuilding's cranes rise over the river skyline and employ thousands, making this one of the coast's real working towns. But it's got depth too: the Old Spanish Fort / Krebs House is one of the oldest structures standing in the entire Mississippi Valley, and the beach boulevard nearby still runs quiet.
Nearby: Walmart, Singing River Hospital (Pascagoula), Ingalls Shipbuilding, Old Spanish Fort (Krebs House), Round Island, Pascagoula Beach Boulevard
Gautier — Coastal convenience, no crowds
Gautier is the quiet pick — greener and calmer than its neighbors, with Shepard State Park's moss-draped bayou trails just minutes from Highway 90. You still get the highway, the hospital, and the Walmart run — you just trade the tourist crowds for pine woods and water views.
Nearby: Walmart, Singing River Health System (nearby), Shepard State Park, Mary C. O'Keefe Cultural Center, Legacy Park development
Bay St. Louis — Old Town charm, working harbor
Bay St. Louis is the coast's most walkable town, and it earns the title honestly — brick sidewalks in Old Town wind past art galleries and second-story balcony bars while shrimp boats still tie up at the Small Craft Harbor under live oaks that were old before the town had a name. Cross the Bay St. Louis Bridge to the east and you're onto the 26-mile man-made beach — the longest man-made beach on planet Earth — so the best sand on the coast is a five-minute drive from your front porch.
Nearby: Walmart Supercenter, Rouses Market, Hancock Medical Center, Small Craft Harbor, Old Town Main St. district, 100 Men Hall
Pass Christian — Old South charm, right on the water
Locals just call it 'the Pass,' and one drive down Scenic Drive tells you why — a canopy of centuries-old live oaks shading a row of grand historic homes that have watched the Gulf for generations. The harbor's masts and marina lights turn an ordinary evening into a postcard, and a walkable downtown keeps the whole scene close.
Nearby: Walmart Supercenter, Pass Christian Harbor, Pass Christian Yacht Club, Scenic Drive Historic District, Downtown Main Street
Waveland — Wide-open beach, small-town pride
Waveland doesn't dress anything up — it just hands you a wide, uncrowded stretch of Beach Boulevard sand and lets the Gulf breeze do the rest. This is a town that took the coast's hardest hit in Katrina and rebuilt itself plank by plank, and you can still feel that grit in every shop window on Coleman Avenue. Buccaneer State Park sits at its back door with campgrounds and nature trails, so you get the beach and the pines in the same zip code.
Nearby: Walmart Supercenter, Buccaneer State Park, Coleman Avenue shops, Waveland Beach, Ground Zero Hurricane Museum
Wiggins — Pine forest, a short run from the sand
Wiggins trades salt air for longleaf pine. De Soto National Forest wraps the whole town in hiking trails, and Flint Creek Water Park gives families a summer destination without a beach drive. For buyers who want land, quiet, and a short shot down Highway 49 to the coast, this is the move.
Nearby: Walmart Supercenter, Memorial Hospital at Stone County, Flint Creek Water Park, De Soto National Forest, Stone County Courthouse
Cat Island — The nearest wilderness
The closest of the barrier islands to Bay St. Louis and Gulfport, Cat Island is undeveloped wilderness — crescent-shaped, ringed by sand, reachable only by boat. It stands between the coast and the open Gulf, part of the natural buffer that's protected this shoreline for centuries.
Nearby: Boat access only, Undeveloped wilderness, Part of the coast's barrier chain
Ship Island — Fort Massachusetts and the ferry run
Ship Island is the coast's front porch to the open Gulf — a ferry runs visitors out to a genuine 1859 fort, Fort Massachusetts, and a beach so clean it feels imported. Part of Gulf Islands National Seashore, it's the barrier island most people actually get to visit.
Nearby: Fort Massachusetts (1859), Seasonal passenger ferry, Gulf Islands National Seashore
Horn Island — An artist's wilderness
Horn Island is raw and untouched — the same dunes and pine thickets that inspired Ocean Springs artist Walter Anderson to paint here for decades. No roads, no development, just wilderness protected as part of Gulf Islands National Seashore.
Nearby: Designated wilderness area, No development, no roads, Walter Anderson's longtime subject
The easternmost barrier island on the Mississippi coast, Petit Bois marks where this stretch of protected shoreline hands off toward Alabama's Dauphin Island. Pure wilderness, accessible only by private boat.
Nearby: Boat access only, Federally designated wilderness, Eastern edge of the barrier chain